

Money Eco: Budget / Expense

- 11.00 Reviews
- 4.7
- Downloads
- 10,000+
Our take on Money Eco: Budget / Expense from Appgk
Money Eco: Budget / Expense is a finance app from Apponance, Inc. that I found most useful when I stopped treating it as a place to record isolated purchases and started using it as a visual checkpoint for my spending habits. Its central promise is simple: bring income, expenses, budgets, and personal-finance reports into one view that is easier to understand than a notebook or a long bank statement.
I like that focus because many budgeting tools make the first step feel heavier than it needs to be. Money Eco is free to install, marked for Everyone, and available for Android devices running Android 7.0 or later. It has reached over ten thousand installs and holds a 4.7 average from a relatively small group of ratings, so I would treat the score as encouraging rather than definitive. The current version is 7.1.0, which gives the app a reasonably current feel.
Why the visual money report matters
The capability that stood out to me is the combination of an expense tracker and personal-finance visualization report. Recording a coffee, a subscription, or a grocery trip is not especially valuable on its own. The benefit appears later, when those entries become a picture of where money is going and how that pattern fits the budget.
That visual approach changes the question I ask myself. Instead of wondering whether I have spent “too much” in a vague sense, I can look for the category or period that is putting pressure on the rest of the month. This is a small but important shift. A list of transactions tells me what happened; a report helps me decide what to change next.
Best Parts of Money Eco: Budget / Expense
Things to Keep in Mind About Money Eco: Budget / Expense
In my experience, this makes the app better suited to reflection than to complicated financial administration. I would not choose it as a replacement for a bank account, a tax tool, or a full household accounting system. I would choose it when I want a clearer daily picture without opening a spreadsheet every time I buy something.
Turning small entries into a useful habit
The real test for a budgeting app is not the first setup screen. It is whether I still want to use it after a busy week. Money Eco works best when I enter purchases close to the moment they happen, while the amount and purpose are still obvious. That routine gives the later report cleaner information and reduces the common problem of trying to reconstruct spending from memory.
News and Features Related to Money Eco: Budget / Expense

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
A useful habit is to make the entry meaningful enough to recognize later, but not so detailed that recording it becomes a chore. For example, I would separate a supermarket visit from a restaurant meal even if both are simply “food.” That distinction makes the report more useful because it shows which behavior is actually changing. I would also avoid creating a different category for every shop; excessive detail can make a budget look precise while making it harder to read.
The strongest result comes from consistent, simple entries rather than perfect financial bookkeeping. That is an important trade-off. If I want exact reconciliation against every bank transaction, I need a more specialized workflow. If I want a practical visual reminder of my spending direction, this approach is more approachable.
Don't want to read the full review?
How I would use the reports in practice
I would begin by entering regular income and the expenses that are easiest to forget, such as recurring services, transport, and small digital purchases. Then I would add everyday spending as it occurs. After several days, the report becomes more informative than a blank budget because it reflects actual behavior rather than an ideal plan.
One useful technique is to review the report at two different speeds. A quick check during the week answers, “Am I drifting toward a problem?” A slower review at the end of the period answers, “Which category deserves a rule or limit next time?” Looking at both views prevents me from overreacting to one unusual purchase while still catching a repeated pattern.
Screenshots
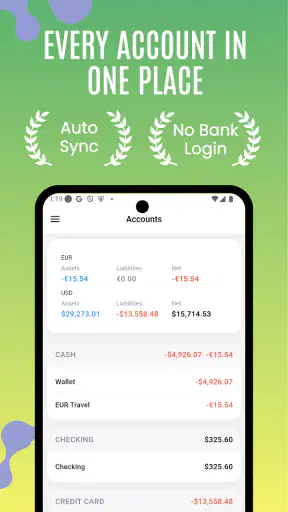
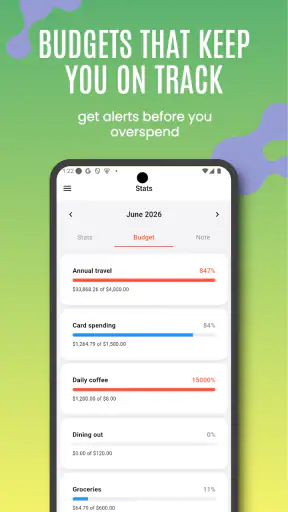
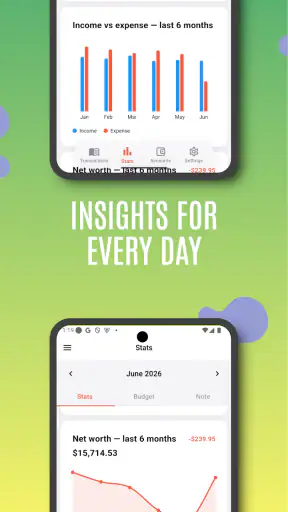
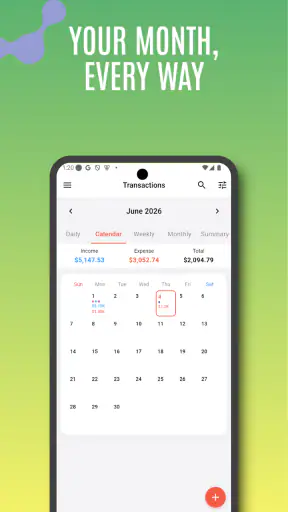
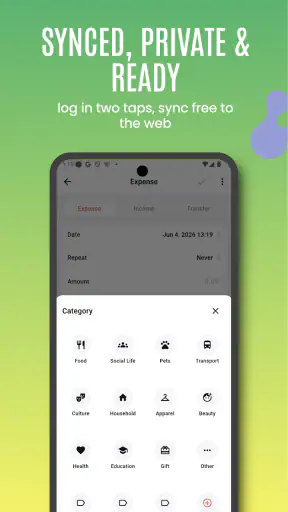
I also found that visual summaries are most helpful when I compare categories with each other, not when I stare at a single total. A large overall number may be unavoidable during a month with a bill or a trip. The more useful clue is often the category that repeatedly expands without being planned. That is where Money Eco can turn a report into a decision: reduce the category, set a more realistic allowance, or accept that the original budget was too optimistic.
What using it feels like day to day
For a realistic example, imagine I am trying to control spending after payday. On the first day, I record my income and the fixed costs I already know about. During the week, I add a few grocery purchases, a ride, a takeaway meal, and a small entertainment expense. None of those entries is dramatic. Together, however, they can show that flexible spending is moving faster than expected.
That is where the app has practical value. I can use the report as a pause before making another discretionary purchase. It does not make the decision for me, and I would not want it to. Instead, it gives me a visible reason to ask whether the next purchase belongs in the plan or whether I am borrowing from a later need.
The same workflow can help someone who shares household costs, although I would keep expectations realistic. If several people are entering expenses, the usefulness of the report depends on everyone using similar categories and recording items consistently. Without that agreement, the chart may still look organized while hiding differences in how each person labels spending.
A better way to review a month
I would not wait until the last day to open the app. A short mid-period review is more actionable because there is still time to adjust. If transport is already high, I can plan the remaining journeys. If food spending is fine but miscellaneous purchases are scattered across several entries, I can identify that leak before it becomes the month’s main surprise.
Another practical tip is to use the report to create one change at a time. Trying to cut every category at once usually produces an unrealistic budget and a quick loss of motivation. Money Eco is more useful when I let the visual summary point to one behavior, such as reducing unplanned meals or checking subscriptions, and then review whether that change made a difference.
This is also where the app differs from a basic notes app. A note can hold amounts, but it rarely encourages comparison between categories and periods. Money Eco’s value is not that entering a number is difficult; it is that the collection of numbers can be interpreted more quickly. Compared with a spreadsheet, it should appeal to people who want less manual formatting and fewer formulas. Compared with a bank app, it offers a more deliberate budgeting perspective rather than simply showing account activity.
Where the simple approach can fall short
The same simplicity that makes Money Eco approachable may frustrate users who expect automatic financial administration. I would not install it assuming that it will replace every other money tool. Someone who needs detailed investment tracking, formal business accounts, complex debt schedules, or precise bank reconciliation should look for an app designed around those tasks.
Manual tracking also requires honesty and consistency. If I forget several cash purchases, delay entries for a week, or place similar expenses in unrelated categories, the report becomes less trustworthy. That is not a flaw unique to this app, but it matters more when the main benefit is visualization. A polished chart cannot correct incomplete input.
There is another subtle limitation: a visual report can encourage false confidence. A neat breakdown may suggest that the budget is under control even when income changes or an annual bill is approaching. I would therefore use Money Eco as a planning aid, not as permission to ignore balances, due dates, or emergency savings. The report helps me see a pattern; I still need to make the wider financial judgment.
Free access and optional spending
The app is free, which makes it easy to try without committing money at the start. It also includes optional in-app purchases ranging from $0.99 to $14.99 per item. I would review those options inside the app before deciding whether any extra is worthwhile, especially if I only need basic expense recording and reports.
For me, the free entry point is important because budgeting tools are personal. An app can look perfect in a description and still fail to fit someone’s routine. Being able to test whether I will actually record expenses is more valuable than choosing a tool based only on a feature checklist.
Who benefits most from Money Eco
I think the best audience is someone who wants a clearer relationship with everyday spending but does not want to build a spreadsheet. It can suit a student managing limited monthly money, a first-time budgeter trying to understand where small purchases accumulate, or a worker who wants a lightweight review of flexible expenses.
It may also help people who already know their income and bills but struggle with the less predictable part of the month. The visual report gives those variable expenses a place in the conversation. Instead of treating them as random surprises, I can watch them develop and decide which ones deserve a limit.
I would be more cautious recommending it to a person who will not enter transactions regularly. If manual tracking feels irritating after a few days, the app’s main advantage disappears. I would also steer a family with complicated shared finances toward a tool built specifically for multiple users and detailed account reconciliation. Money Eco is strongest when one person wants a straightforward overview and is willing to maintain it.
What I would check before settling on it
Before making it my main budgeting tool, I would spend a week testing a complete routine rather than only opening the app once. I would record fixed costs, everyday purchases, and one irregular expense, then see whether the report answers practical questions quickly. Can I tell which category is growing? Can I understand the period without remembering every entry? Does reviewing the report lead to a decision?
I would also pay attention to how much effort categorization takes. The right level is the one I can maintain on a tired day. If I need to pause over every purchase, I would simplify the categories. If the summary becomes too broad to teach me anything, I would add only the category that would change a future decision. This balance is more important than having a long list of labels.
Finally, I would keep a separate awareness of obligations that do not appear in ordinary daily spending. A budget report is most useful when it sits beside, rather than replaces, the bigger picture of balances and upcoming commitments. Used that way, the app becomes a practical checkpoint instead of a source of misplaced certainty.
My final take on the visual budgeting approach
Money Eco: Budget / Expense earns my recommendation for people who need to see their spending more clearly and are comfortable entering it themselves. Its standout capability is not complicated financial machinery; it is the way recorded expenses become a visual report that can prompt a better choice before the month gets away from me.
I appreciate the focused experience from Apponance, Inc., the free starting point, and the Everyone age rating. The 4.7 average and over ten thousand installs suggest that it has found an audience, although I would still judge it by my own willingness to keep using it. The optional purchases are worth considering, but they do not change the basic question: will the reports make my spending easier to understand?
For a simple personal budget, the answer can be yes. I would use it to identify leaks, review flexible spending, and build a repeatable weekly money check. I would skip it if I needed automatic account management, advanced financial planning, or a detailed shared-household system. If your main problem is not a lack of financial information but a lack of a clear view, Money Eco is a sensible app to try.
Money Eco: Budget / Expense FAQ
What is Money Eco: Budget / Expense used for?
Money Eco: Budget / Expense is designed to help you monitor personal finances in one place. You can record income and spending, organize transactions by categories, review where your money goes, and follow your budget over time. It is useful for everyday expense tracking, planning monthly limits, and developing a clearer understanding of your financial habits.
Is Money Eco: Budget / Expense easy to use for beginners?
Yes, the app is generally approachable for beginners because its main purpose is straightforward: add your income and expenses, assign categories, and review the resulting summaries. The experience becomes more useful when you consistently enter transactions. Users who prefer detailed financial planning may need some time to configure categories, budgets, and personal preferences before everything feels fully organized.
Can I create budgets and track spending categories?
Money Eco: Budget / Expense supports the kind of budgeting workflow most users expect from a personal finance app. You can separate spending into categories such as food, transportation, bills, shopping, or entertainment, then compare your activity with planned limits. This makes it easier to identify overspending and adjust habits before the end of the month.
Does Money Eco: Budget / Expense connect to my bank account automatically?
You should not assume that every transaction will be imported automatically. Depending on the version, platform, region, and available features, the app may rely primarily on manual entry or offer limited synchronization options. Before downloading, check the current Google Play or App Store listing for supported bank connections, data-import tools, and any restrictions that may apply to your country.
Is my financial information safe in Money Eco: Budget / Expense?
Because the app can contain sensitive information about your income, purchases, and financial routines, privacy should be checked before regular use. Review its current privacy policy, permissions, backup options, and any cloud-synchronization settings. Avoid entering passwords, card PINs, or complete banking credentials unless the official app documentation clearly explains how that information is protected.











